Disclaimer: This content is provided for educational and entertainment purposes only and does not constitute professional advice. We do not guarantee the accuracy or completeness of any information presented. We are not liable for any actions taken based on this content. For specific issues or decisions, we recommend seeking professional advice.
I’ve been watching the Australian housing market for years, and I can’t remember a stretch quite like this one. Not because the falls are dramatic in some crash-movie sense. They’re not. It’s the mood that’s shifted.
For most of the last decade, every conversation about property went the same way. Prices went up, people complained, prices went up again. Now, halfway through September 2026, the conversation has flipped. Values have been sliding for five months straight, and the decline has spread to the vast majority of capital city suburbs.
So let’s talk about what that actually means, minus the hysteria.
The short version
National home values peaked back in March and have been drifting down since. Cotality’s index puts the fall at a bit over 3.5% from that peak, though its daily measure of the five big capitals shows a steeper drop of around 5%.
Sydney is leading the way down. Melbourne isn’t far behind. Brisbane, Adelaide, Perth and Canberra have all joined in, which is the part that surprised a few people. Perth in particular was flying not that long ago.
Darwin is the one holdout. Make of that what you will.
Why it’s happening now
Two things collided, and I think that’s the key to understanding this cycle.
Interest rates went the wrong way
Most people spent 2025 waiting for cuts. Instead we got rises, and the cash rate has stayed uncomfortably high. Borrowing capacity has shrunk as a result.
This is the bit I’d emphasise if you’re trying to make sense of it. It isn’t just that repayments are more expensive. It’s that the bank will simply lend you less than it would have eighteen months ago. Same income, same deposit, smaller number at the end.
The tax changes in the May budget
Negative gearing was restricted and capital gains tax increased. HSBC’s Paul Bloxham has been fairly direct in saying the market weakened quickly after those changes landed.
Whether you think that policy is good or bad isn’t really my point here. The practical effect is that investor demand has thinned out considerably, and investors were doing a lot of the heavy lifting in some markets.
The part that surprised me: expensive homes are falling hardest
I would have guessed the opposite. Usually the top end holds its nerve because those buyers are less rate-sensitive.
Not this time. Cotality’s data shows upper-quartile house values in Sydney and Melbourne are down more than 10% from peak, while cheaper properties have held up far better.
There’s a logic to it once you sit with it. Big homes need big loans. Big loans are exactly what got harder to secure. And when the tax treatment of investment property changes, the people making the largest investment decisions react first.
Units, meanwhile, are doing comparatively well. When affordability bites, people don’t stop buying. They buy smaller.
What this looks like on the ground
Numbers are one thing. Here’s what’s actually changed in how property is bought and sold.
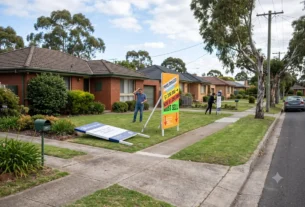
Homes are taking noticeably longer to sell. The national median has stretched to around 39 days, up from 28 a year ago. If you’ve had a property listed for six weeks and you’re starting to panic, that’s now fairly normal.
Sellers are accepting less. Typical vendor discounting has widened to roughly 4% off the original asking price.
Auctions have cooled. Clearance rates have been under 50% since late May. Anecdotally, I’ve heard more stories this winter about properties passing in and selling quietly afterwards than I have in years.
Stock is piling up. New listings are actually down on last year. Total listings are up around 24%. Those two facts together tell you everything — homes aren’t being pulled to market in a panic, they’re just sitting there.
That last point matters more than people realise. It’s the difference between a market with too many sellers and a market with not enough buyers. Right now it’s clearly the second one.
Meanwhile, rents are still climbing
Here’s the frustrating bit. Falling prices sound like good news for anyone locked out of the market. But rents have gone up about 5.7% over the past year, and vacancy rates are still historically tight.
I find this genuinely irritating to write about, because it undercuts the cheerful “housing is getting cheaper” headlines. If you’re renting and saving a deposit, you’re probably feeling the squeeze on one side while the finish line moves slightly closer on the other. Net effect: not much relief.
How far might this go?
The forecasts have been revised down repeatedly through the year, which is usually a sign forecasters are behind the curve rather than ahead of it.
The rough consensus now sits somewhere around a 10% peak-to-trough fall, with ANZ and NAB in that ballpark and HSBC a bit more pessimistic at 13%. For context, the 2022–23 downturn was closer to 8%.
But I’d treat all of that with healthy scepticism. Forecasts have a poor record in this market, in both directions.
Reasons it probably won’t become a crash
A few things are holding the floor up:
- Unemployment is still low. Forced sales are what turn a correction into a collapse, and we’re not seeing them in any real volume.
- Population growth hasn’t stopped. More people, same shortage of homes.
- Building is hard. Costs, labour, approvals. New supply isn’t arriving fast enough to make a dent.
- Some investors are sitting tight. Selling now means triggering a CGT bill under the new rules. A fair few will simply hold.
Cotality’s Gerard Burg described it as potentially a prolonged downturn rather than an enormously deep one. That framing rings true to me.
What I’d actually do, depending on where you sit
If you’re buying
You have leverage you haven’t had in years. Use it.
Offer below asking. Ask for longer settlement terms. Walk away from properties where the vendor won’t move — there are others, and the listing count proves it.
One thing I’d look at first: get your borrowing capacity checked before you fall in love with something. The number may have changed since you last checked, and finding that out at contract stage is a horrible experience.
If you’re selling
Price to today’s market, not to what your neighbour got in early 2025. I know that’s unwelcome advice. It’s also the single biggest factor in whether a property sells in four weeks or four months.
Overpriced listings go stale. Stale listings attract lowball offers. You end up worse off than if you’d been realistic on day one. I’ve watched this play out enough times to be confident about it.
If you’re investing
Yields are the best they’ve been since around 2019, which sounds encouraging. Just remember that higher yields here are partly a function of falling prices, not booming rents.
Run the numbers properly. Holding costs are high and the tax treatment has genuinely changed. The old back-of-envelope maths doesn’t work anymore.
If you already own and you’re staying put
Honestly? Do nothing. Paper losses only matter if you’re selling. If your job is secure and your repayments are manageable, this cycle is noise.
A bit of perspective
A 10% fall would roughly return prices to where they were in late 2024. That’s it. Not 2015, not 2019 — late 2024.
For someone who bought at the peak this year, that’s a real and uncomfortable thing. I don’t want to breeze past it. But in the context of how far prices ran up beforehand, it’s a correction rather than a catastrophe.
There’s a reasonable argument, made by a few analysts recently, that a long stretch of flat nominal prices would actually be the healthiest outcome available. Affordability improves slowly, nobody gets wiped out. Not exciting, but sensible.
Australians All
Latest posts by Australians All (see all)
- What’s Actually Happening to Australian Property Prices Right Now - September 18, 2026
- My Journey into Queensland Commercial Real Estate: A Practical Investment Guide - September 15, 2026
- What Is a Freight Forwarder? A Plain English Guide for Australian Importers and Exporters - August 31, 2026